Guide · Options
Selling puts: what it means, what you risk and how to record it

Tortuga Trades · · 10 min
Selling a put means collecting a premium today in exchange for committing to buy 100 shares at a set price if you are asked to. That is where almost everything written on the subject stops. The questions left are the ones that matter afterwards: how much you can really lose, what your broker requires to let you do it and, if you get assigned, what price you actually paid for those shares. That last one has two different answers, and you need to record both.
What selling a put means
A put is the right to sell a stock at a set price —the exercise or strike price— until a given date. Whoever buys it pays for that right; whoever sells it gets paid. If you sell the put, you take the other side: the obligation to buy the shares at the strike if the buyer decides to exercise. That is how the Options Industry Council (OIC) puts it: if the stock drops below the strike, you may be assigned, and then you buy at the strike.
Each contract on US stocks normally covers 100 shares. The premium lands in your account when you sell, but what it buys is not income: it is a commitment that stays alive until the option expires, you buy it back, or you are assigned.
You can be assigned before expiration
Options on US stocks are American-style: whoever holds the long put can exercise it on any day before expiration, and therefore the seller can be assigned at any time. The OIC adds that when a put is deep in the money, professionals usually exercise it early.
At expiration, the US clearing house (OCC) automatically exercises options that finish a cent or more in the money, unless the buyer instructs otherwise. The same FAQ is clear that there is no magic number that guarantees the seller won't be assigned. Assignments are allocated randomly among sellers, based on net positions after each day's close: if you buy the put back before the close, you can no longer be assigned that night.
Cash-secured put or naked put
The same trade can be done in two ways, and the difference is not in the option but in what you have behind it. In a cash-secured put you set aside, from the start, the money needed to buy the shares if you are assigned. In a naked put you don't: according to the OIC, if you are assigned you would have to sell other assets quickly or borrow to honor it.
The option's risk is the same in both cases. What changes is whether you can honor it. The OIC describes the cash-secured put as having a risk profile identical to the covered call, and puts its maximum loss at the strike minus the premium: substantial.
What Interactive Brokers asks of you
IBKR organizes options into four permission levels. Level 1 allows covered calls only; level 2 adds "covered puts" and defined-risk strategies; level 3, uncovered shorts; level 4 is full permissions. On the same page, another IBKR table explicitly places short puts at level 3. Each level has to be requested and qualified for: check it in your permissions request.
What IBKR does publish is how much it holds back. In its requirements table for US options, a short put in a cash account requires the full strike: by definition, a cash-secured put. In a margin account the requirement is lower and comes from a formula: the premium plus the greater of two amounts, 20% of the stock price minus the amount the put is out of the money, or 10% of the strike.
At DEGIRO, according to its help center, derivatives are only available on the Active, Trader and Day Trader profiles, not the basic one. Which options markets it offers and what collateral it requires for a short put are not published on any page we have been able to verify: check in your account.
A worked example, numbers in full
Suppose a stock trades at $100 and you sell a put with a 95 strike and one month to expiration, for a premium of $2 per share. The figures are an example, not a real trade.
The maximum loss is what you would have if the stock went to zero: you buy at 95 something worth nothing, and only the premium is left. With those numbers, what you see at expiration depends on where the stock ends up:
| The stock ends at… | What happens | Economic result |
|---|---|---|
| $98 (above 95) | The put expires worthless. You buy nothing. | +$200: you keep the premium |
| $94 (between 93 and 95) | You are assigned: you buy 100 shares at $95 that are worth $94. | −$100 on the shares + $200 premium = +$100 |
| $85 (below 93) | You are assigned: you buy 100 shares at $95 that are worth $85. | −$1,000 on the shares + $200 premium = −$800 |
Measured against the cash set aside, the $200 premium is 2.1% in one month (200 ÷ 9,500). It is a useful figure for comparing one put with another, as long as you remember that the second and third scenarios exist.
If you are assigned, you have two purchase prices
This is what almost no guide tells you. When you are assigned, what price did you pay for the shares? It depends on why you are asking, and both answers are correct on their own ground.
The economic price: strike minus premium
To decide what to do with the shares, what counts is what they really cost you. The OIC puts it this way: the net price you pay per share is the strike minus the premium you collected when you sold the put. In the example, 95 − 2 = $93. It is your breakeven. The calculation with commissions and several assignments is in how to calculate your cost basis after a put assignment.
The tax price: the market value on the day
The Spanish tax authority doesn't do that sum. Under Spanish personal income tax (IRPF), options trades produce capital gains or losses (article 37.1.m of the Ley del IRPF, the income tax act), and the Dirección General de Tributos (DGT, the Spanish Treasury body that answers taxpayers' queries) answered exactly this case —a sold put that ends up exercised— in ruling V0137-23. Its position has two parts:
- The option has its own result:the premium collected minus the difference between the strike you pay and the market value of the shares, minus the trade's expenses.
- The shares are deemed acquired at market value, not at the strike nor at the strike minus the premium.
With the third scenario of the example, and assuming the market value on the assignment day is $85:
If you ended up selling the shares at 85, both routes would add up to the same −$800, but they split it differently. On the economic route the loss is not realised yet: you hold shares that cost you 93 and are worth 85. On the tax route, the option has already closed with an $800 loss and the shares start from 85, so when you sell them only their move from there will be taxed. The total matches; the pieces don't, and they don't necessarily fall in the same year.
If the put is not exercised, ruling V2172-21 establishes that the premium is not taxed when collected, but at expiration, at exercise, or when the position is closed if that comes first: if it expires, the gain is the premium minus expenses; if you buy it back, the difference between the premium collected and the premium paid. The result goes into the savings tax base (base del ahorro). The same ruling holds that the rule blocking losses when you buy the same securities back within two months (one year if unlisted; article 33.5 f and g) does not apply to options trades. This is general information, not tax advice.
How to record it without mixing the two figures
If you keep the record yourself, the simplest way not to confuse them is to write down both pieces of data on the assignment day itself, because reconstructing the market value months later is far harder.
| Data | What it is for |
|---|---|
| Strike, net premium and sale date | Working out the economic price (strike − premium) and knowing which contract was assigned. |
| Assignment date | Decides which tax year the option’s result belongs to. |
| Market value of the stock that day | It is the shares’ tax acquisition value and goes into the option’s result. |
| Tax result of the option | Premium − (strike − market value) − expenses. Goes into that year’s return. |
| Economic price of the shares | Strike − premium. Tells you above what price you sell without a loss. |
If you chain puts, assignments and covered calls on the same stock, the unit of record stops being the trade and becomes the whole cycle. That is covered in how to track the wheel strategy.
What you will see in Tortuga
Tortuga imports options from Interactive Brokers and tastytrade. DEGIRO options are not imported: you can enter them by hand from Portfolio with "Add position", and when you close them you choose whether you closed it, it expired, or it was assigned.
- The label is "Short Put".It doesn't say "cash-secured" because Tortuga cannot check whether you had the cash set aside.
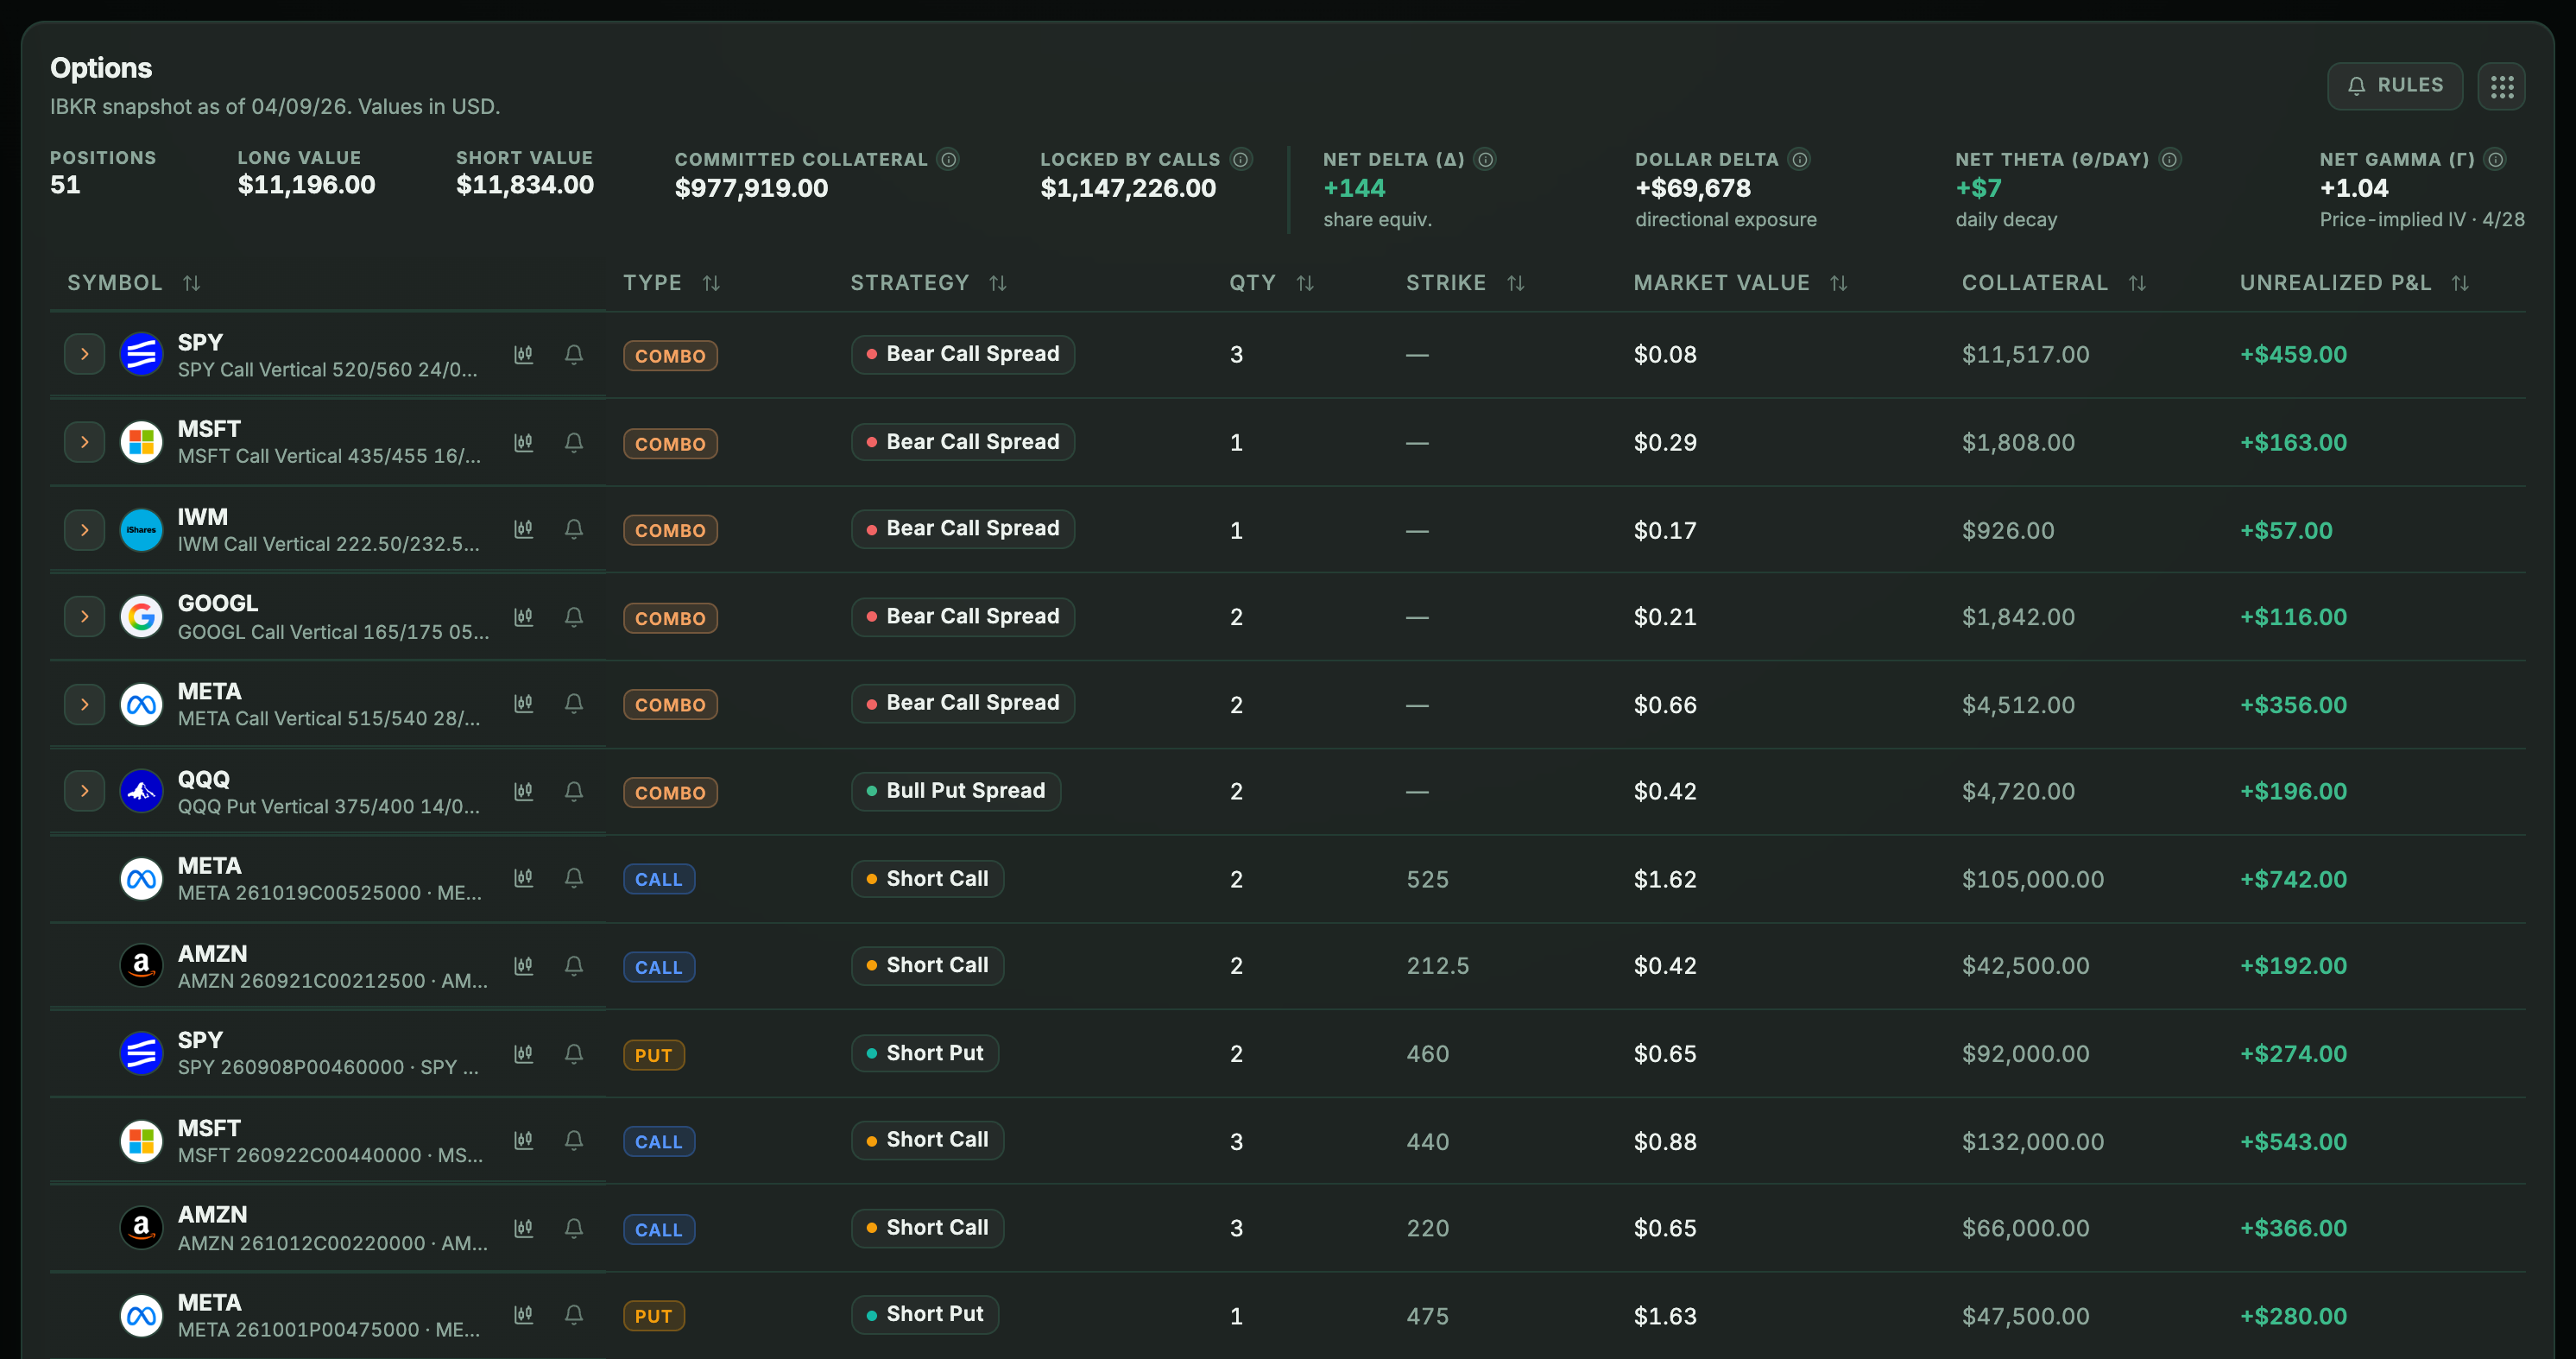
- The "Collateral" columnin Portfolio › Options (hidden by default; you turn it on from the column organizer) shows, for each short put, the strike × 100 × contracts. It is what you would have to pay if you were assigned, not the margin your broker holds back. The total appears at the top as "Committed collateral".
- The premium counts in "Premiums" when the contract closes, not when you sell it. With one exception at Interactive Brokers: if you are assigned, the way IBKR delivers it the premium sits inside the shares' "Avg cost" (strike − premium) and doesn't show in "Premiums".
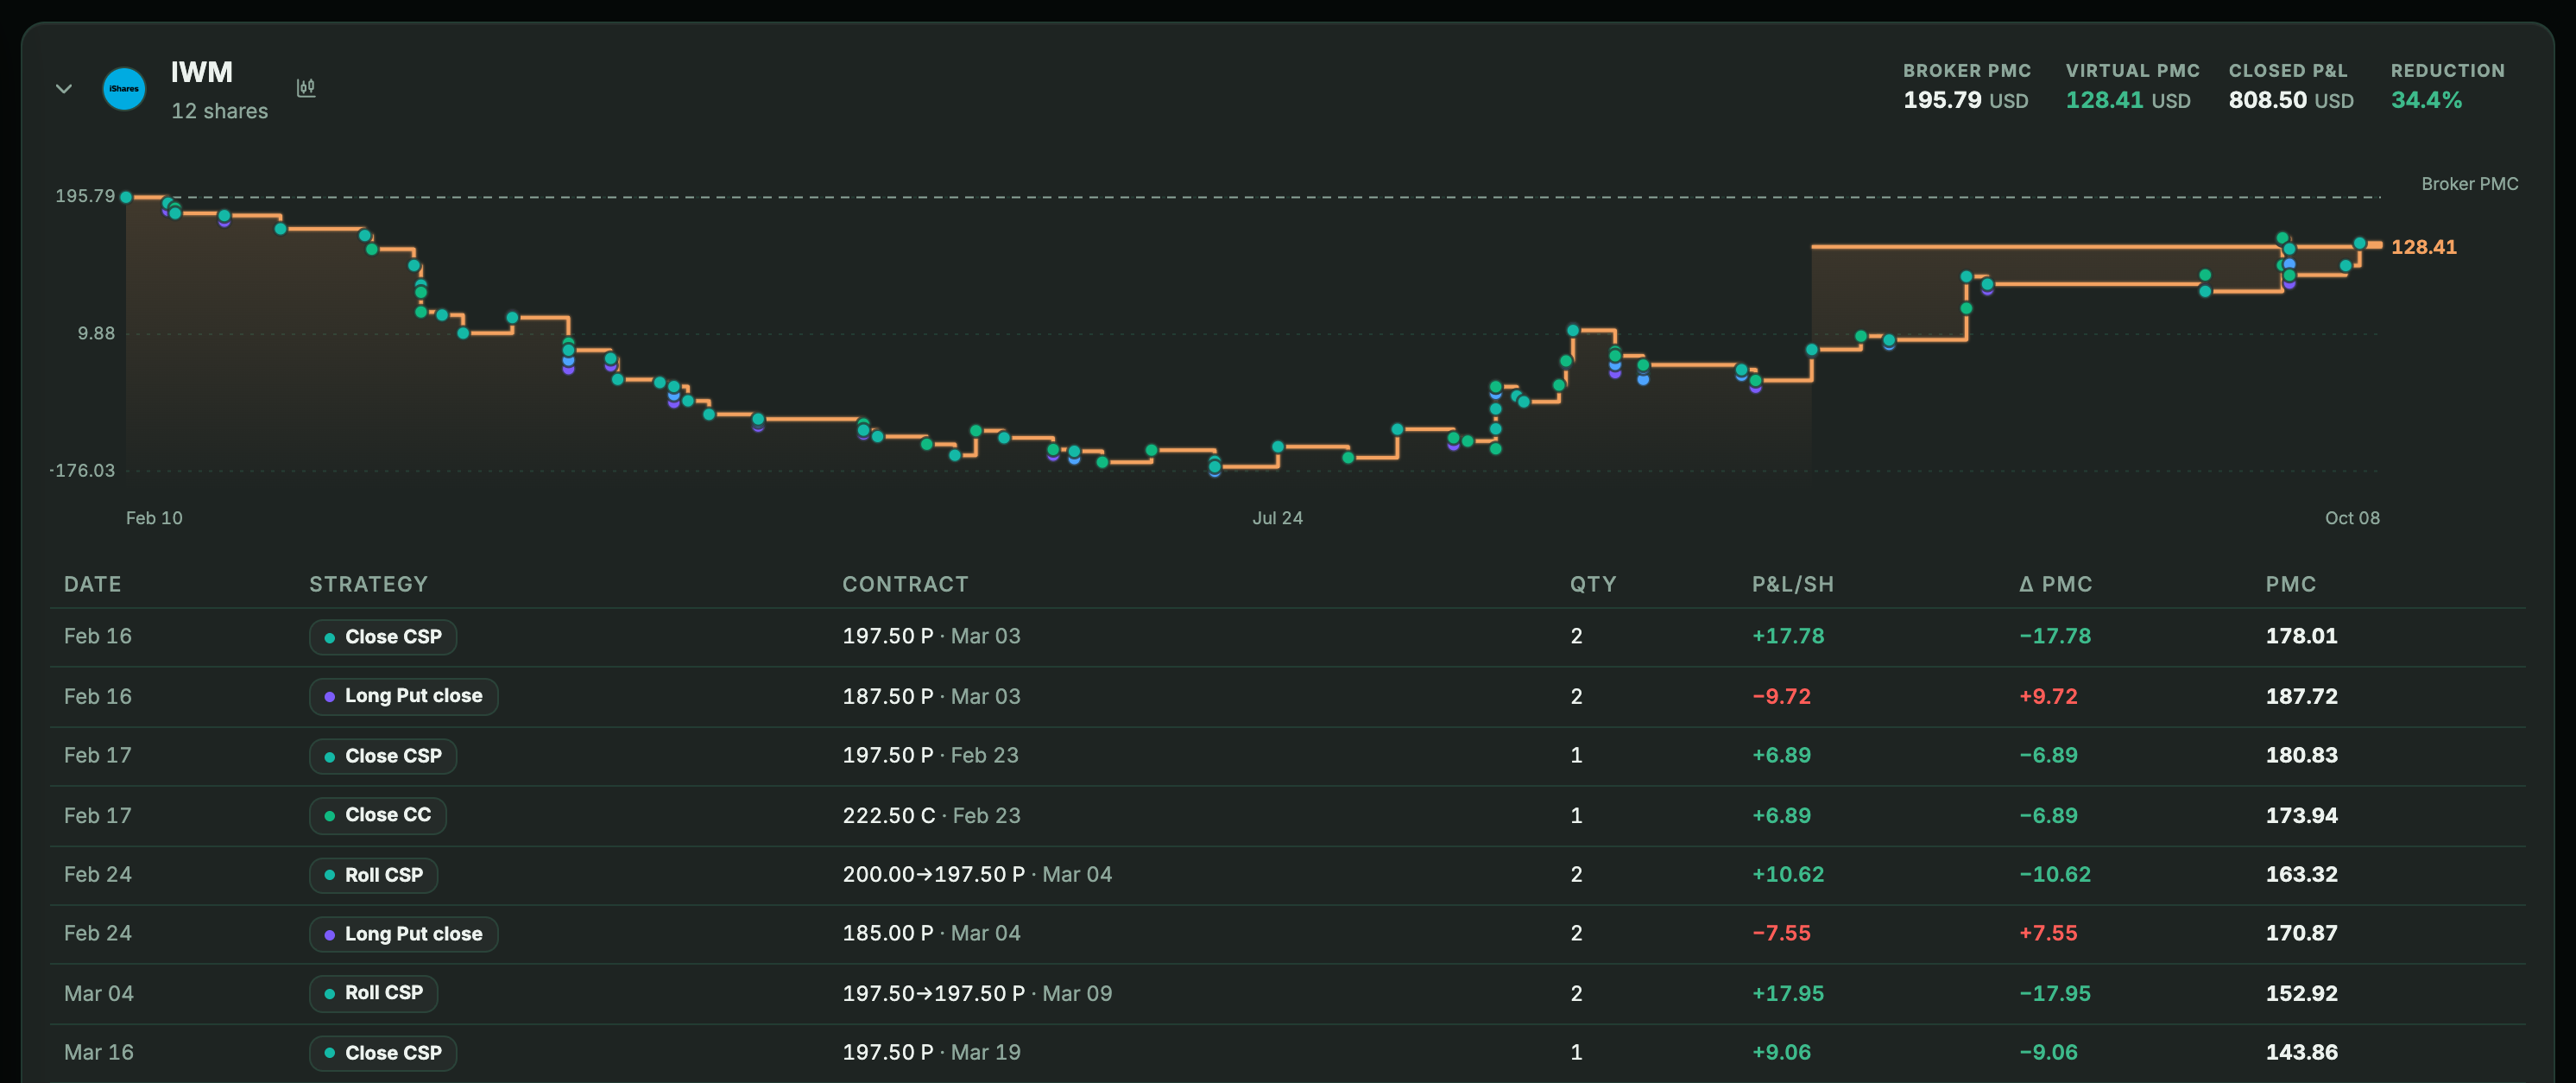
If you have a positions snapshot (IBKR or the tastytrade API connection), Portfolio › Options › Underlyingsshows next to each stock the "Broker PMC" (the broker's average cost) and a "Virtual PMC" that subtracts the closed premiums on it.
Before selling: Option Lab
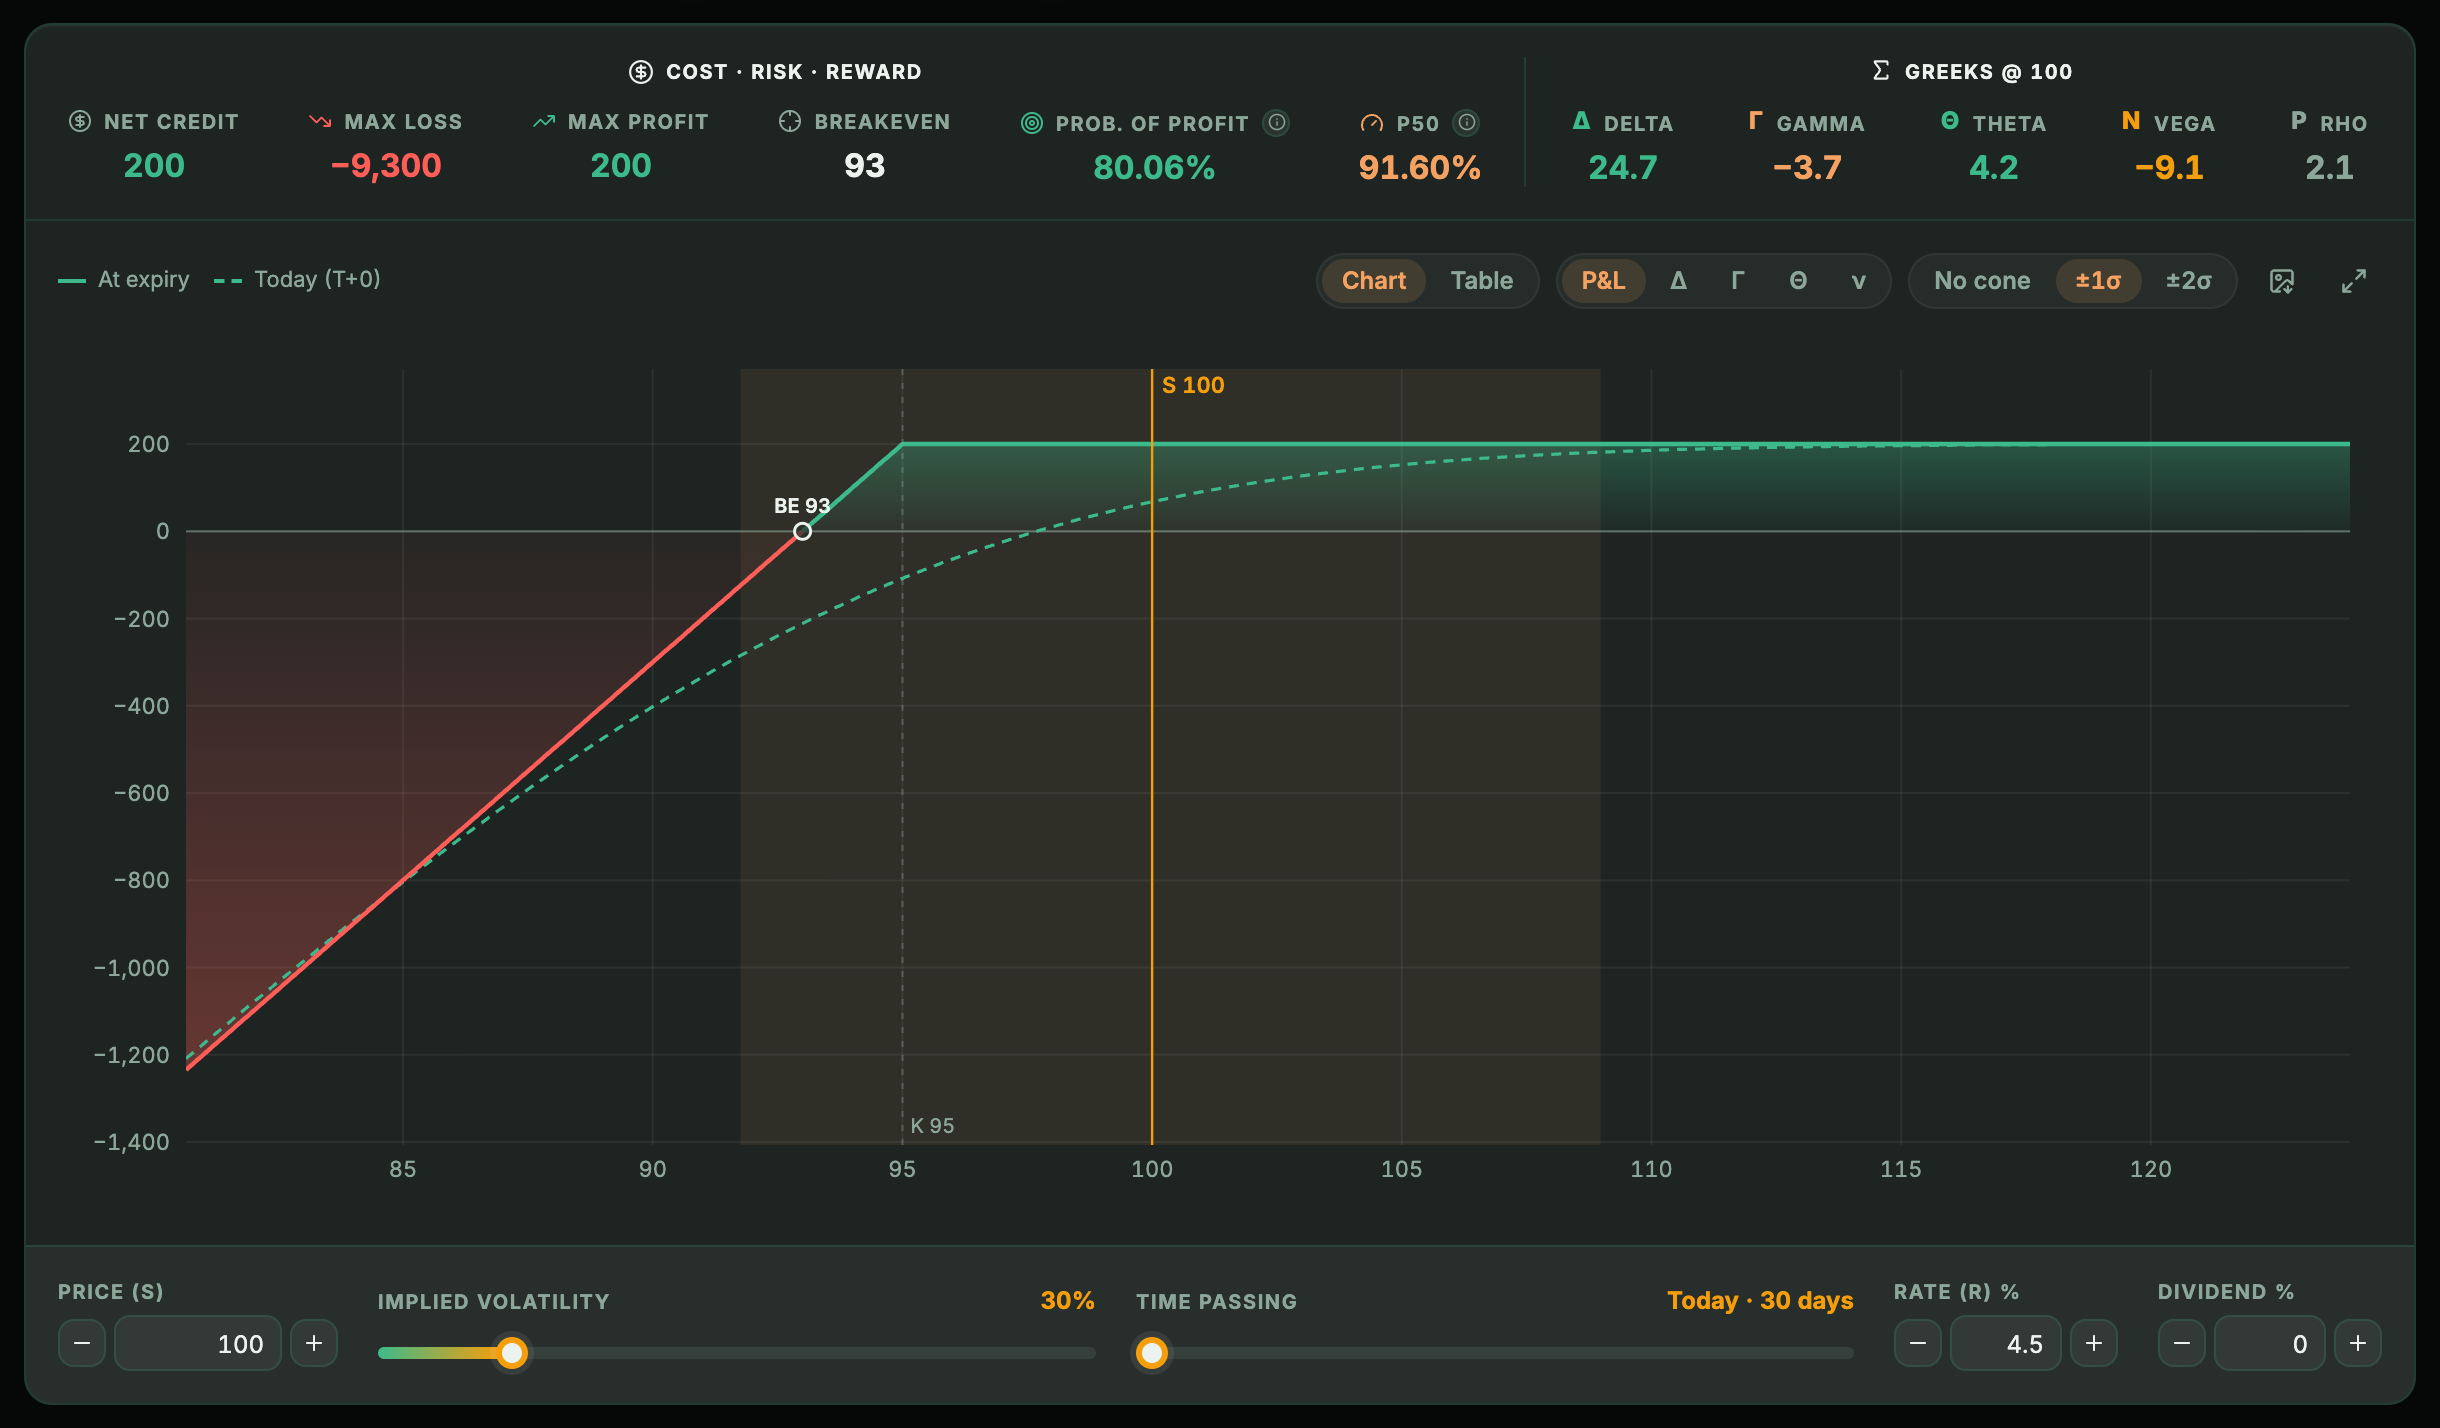
In Market Lab, Option Lab has a "Short Put" template. With this guide's example —a 95 put sold for 2— it shows a "Max loss" of $9,300 and the "Breakeven" at 93, plus a probability of profit and the Greeks. These are theoretical Black-Scholes prices: real chains only load for US tickers (for anything else you enter price and volatility by hand), it doesn't read your positions from Portfolio, and it doesn't model early assignment, commissions or margin.
Keep reading
- How to calculate your cost basis after a put is assignedYou were assigned and your shares are worth less than you paid. The real number subtracts the premium you collected, and almost nobody gets it right.
- How to track the wheel strategy: premiums, assignments and cost basisThe wheel takes five minutes to explain and three months to get out of hand. What to record on each turn to know whether you are really making money.
- What happens when an option expiresThree outcomes, not two. Exercise, assignment and expiration, with the buyer’s and the seller’s numbers side by side.